PILLAR FIVE · THE RECEIPTS
Personal
Finance Basics
The foundations everything else is built on. Budgeting, saving, debt, credit scores, emergency funds, salary negotiation. Nobody is made to feel behind for starting here - this is where every rich girl begins. The door is open at every rung of the ladder.
✦ How to build a budget that actually works - without feeling like you're depriving yourself
✦ What an emergency fund is, how much you need, and how to build one from scratch
✦ The difference between good debt and bad debt - and how to deal with both
✦ How your credit score works and the simple habits that improve it over time
✦ How to negotiate your salary - what to say, when to say it, and how to stop leaving money on the table
Every rich girl started somewhere.
This is where
most of them began.
Before the ISAs and the pension contributions and the investment portfolio - there are foundations. A budget. An emergency fund. A credit score you understand. Money you're not losing to debt you don't need to carry. This pillar builds those foundations - wherever you're starting from.
BUILD IN THIS ORDER
The six foundations - in order
FOUNDATION ONE
Emergency Fund
Three to six months of essential expenses. Held in cash. Easy access. Untouched unless something genuinely goes wrong. Without this - any financial shock goes straight on a credit card. Build this before anything else.
FOUNDATION TWO
Clear High Interest Debt
Any debt above 5-6% interest is costing you more than most investments will return. Credit cards, buy now pay later, overdrafts - clear these before investing. The return on clearing a 20% credit card is guaranteed. Markets aren't.
FOUNDATION THREE
Budget That Works
Not a spreadsheet you abandon by Wednesday. A system that actually fits your life. Know what comes in, what goes out, and what's left. Without this - everything else is guesswork. The 50/30/20 rule is a good starting point.
FOUNDATION FOUR
Grow Your Income
Your salary is your biggest wealth building tool. Negotiate it. Ask for reviews. Know your market rate. A £5,000 pay rise compounded over a career is worth significantly more than cutting your coffee budget for a decade.
FOUNDATION FIVE
Protect Your Credit
Your credit score affects your mortgage, your rental applications, your loan rates. It's not complicated - pay on time, keep utilisation low, don't apply for too much at once. Simple habits. Serious long term impact.
FOUNDATION SIX
Then Invest
Once foundations one to five are in place - now you invest. ISA open. Pension contributions maximised. Long term wealth building begins. Not before. In this order. Every time.
The full receipt on personal finance basics is coming. 🖤
THE BUDGET FRAMEWORK
The 50/30/20 rule explained
50%
NEEDS
The non-negotiables. Things you genuinely cannot live without.
Rent · Groceries · Utilities · Transport · Minimum debt payments
30%
WANTS
The things that make life enjoyable. Not guilty pleasures - just life.
Eating out · Subscriptions · Shopping · Holidays · Entertainment
20%
SAVE & INVEST
The future you. Emergency fund, ISA, pension top-up, debt overpayment.
Emergency fund · ISA contributions · Pension top-up · Debt overpayment
The 50/30/20 rule is a framework, not a rulebook. If you live in London on an average salary, 50% for needs might feel impossible. Adjust the percentages to your reality - what matters is the principle: needs first, fun second, future always. 🖤
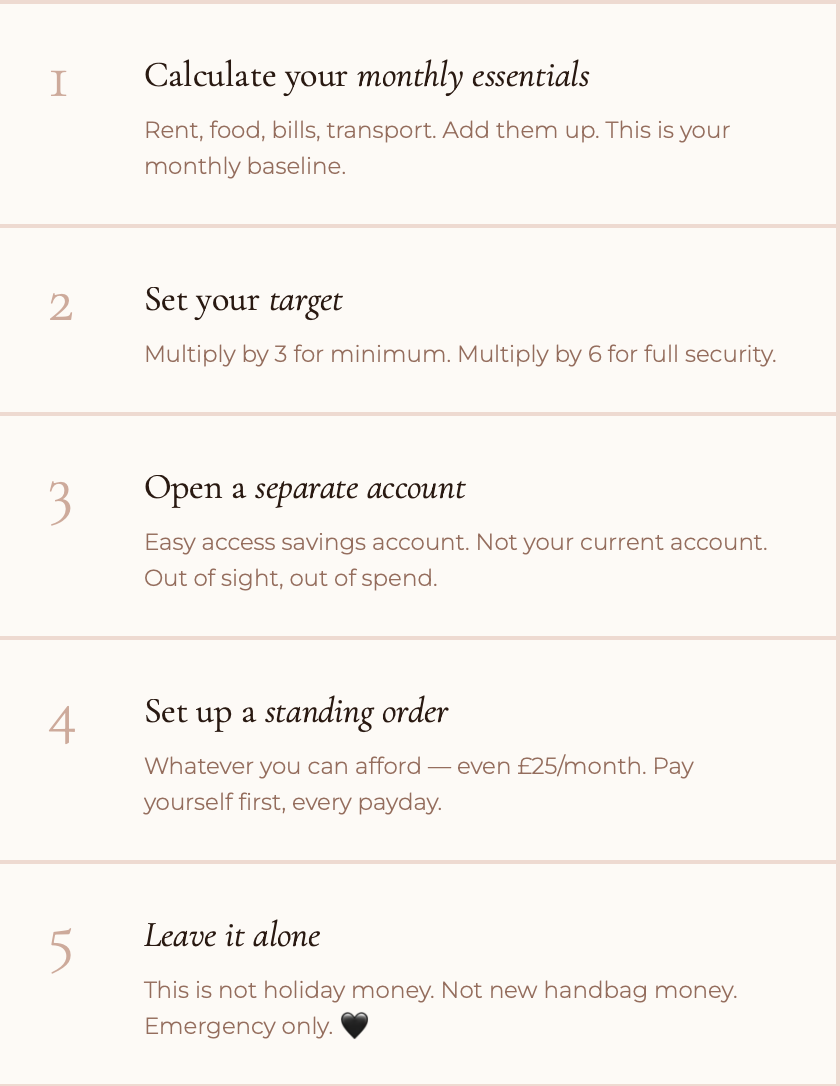
Build your emergency fund
in five steps
An emergency fund is not optional. It's the thing that stops every financial shock becoming a financial crisis.
Here's how to build one from zero - without needing a lump sum to start.
Want the full breakdown including how much you actually need and where to keep it?
Read the full receipt - coming soon 🖤
Personal Finance Receipts
Pay yourself first.
Every single month.
Before the nights out.
Before the online shopping.
Before anything else.
Your future self is not going to thank you for the ASOS order. She will thank you for the standing order. 🖤
YOUR HOMEWORK
The financial audit checklist
Do you know exactly how much comes in every month after tax?
Open your bank app. Check your last three payslips. Write it down.
FOUNDATION
Do you know exactly how much goes out every month?
Direct debits, subscriptions, rent, bills - everything. No guessing.
BUDGETING
Do you have an emergency fund of at least one month’s expenses?
In a separate account. Easy access. Untouched. If you do, do you have at least 3-6 months?
EMERGENCY
Do you know your credit score?
Check with Experian, Equifax or Credit Karma - all free.
CREDIT
Do you know the interest rate on every debt you’re carrying?
Credit cards, overdraft, loans. List them. Highest rate first.
DEBT
When did you last check your salary against your market rate?
LinkedIn Salary, Glassdoor, industry reports. If it’s been over a year - check now.
EARN MORE
Do you have a standing order set up to save each month?
Even £25 per month. Automatic. Payday. Non-negotiable.
SAVINGS
Keep these in the notes on your phone. Write them down on a piece of paper to wake up to. Whatever holds you accountable.
This is your future - and you are in full control of it.
KEEP EXPLORING
More receipts to discover
THE WEEKLY RECEIPT